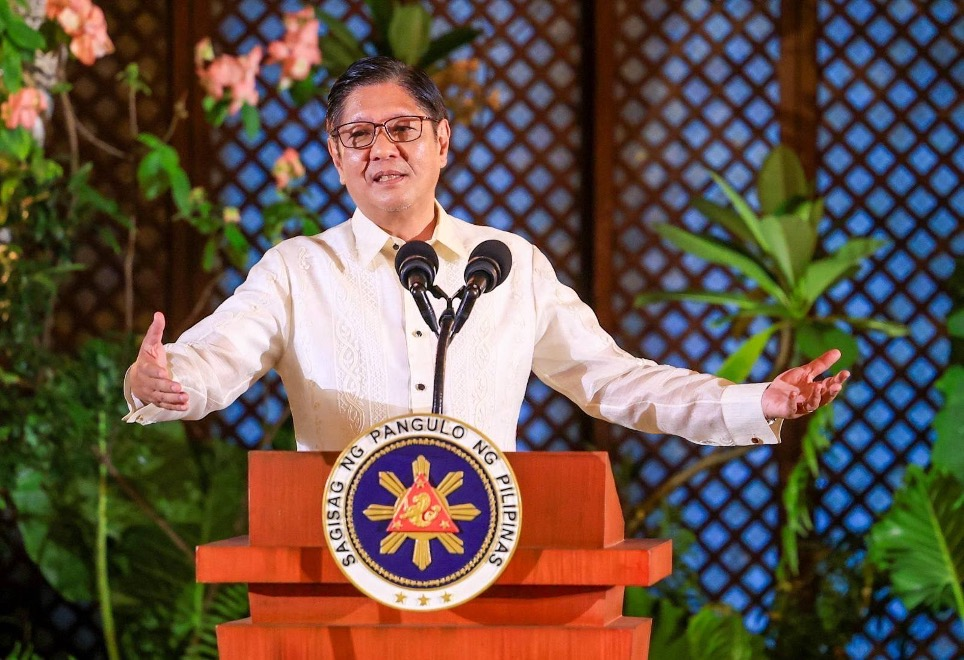

In the latest economic and political developments across Asia, Moody’s Analytics said the Philippines emerged as a key focus following its 12 May midterm elections. Early unofficial results suggest that President Ferdinand Marcos Jr.’s administration has secured a narrow but strategically critical victory over a coalition aligned with the Duterte political faction.
The result solidified the Marcos administration’s legislative influence, allowing it to continue its economic and governance agenda without major political disruption.
This outcome carries significant implications for economic stability and investor confidence in the Philippines. Continuity in policy direction means the Marcos government can maintain its current trajectory on infrastructure spending, digitalization, and initiatives to boost foreign direct investment—pillars of its economic strategy since taking office.
A stable political backdrop also strengthens the administration’s hand in navigating global economic headwinds, particularly in the context of fluctuating commodity prices, regional inflation pressures, and capital flow volatility.
Elsewhere in Asia, the economic landscape remains mixed. The IMF’s approval of a $1 billion disbursement to Pakistan highlights progress in restoring economic stability there, while Thailand is expected to report a doubling of quarterly GDP growth (to 0.8%) driven by strong exports and rising government spending.
Singapore posted impressive export gains in April, while Japan’s economy contracted 0.2% in Q1 due to weakened exports, even as core inflation likely jumped to 3.8% in April—its highest since early 2023—largely due to temporary government policy shifts.
In China, April data is expected to show slowing industrial production and retail sales growth, reflective of ongoing trade tensions and a domestic slowdown. A softening in fixed-asset investment is also anticipated, though monetary easing efforts—such as an expected 10 basis point cut in loan prime rates—aim to stabilize the economy.
Trade relations with the U.S. also saw a thaw over the weekend, as both sides agreed to reset tariffs to pre-April levels and resume talks over a 90-day window. While this détente is a positive signal for global markets, uncertainty persists for other U.S. trading partners.
In summary, while regional economies continue to wrestle with uneven recovery paths and policy recalibrations, the Philippines’ midterm election result offers a measure of political and economic clarity. For markets and investors, the likely affirmation of the Marcos administration’s mandate reinforces expectations of steady economic policymaking in the near term.