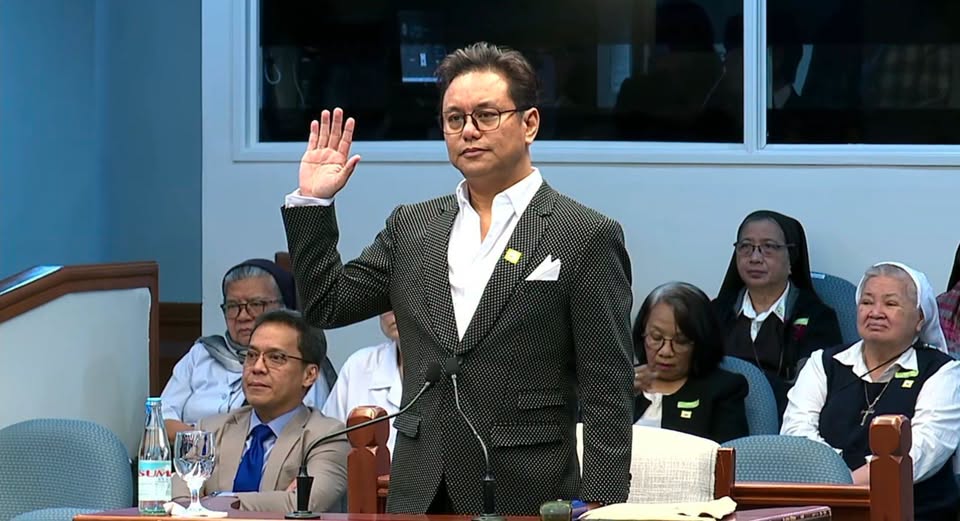

MANILA – Bureau of Internal Revenue (BIR) records showed that Vice President Sara Duterte declared Php 4.65 million in non-compensation income in 2021, exceeding the Php 2.36 million she received in compensation while serving as Davao City mayor, according to testimony presented before the Senate impeachment court on Thursday, October 8.
BIR Office of the Commissioner chief of staff Atty. Anne Loraine Garcia-Marquez testified that Duterte’s 2021 income tax return reflected gross compensation income of Php 2,361,252 and non-compensation income, classified as sales, revenues, receipts or fees, amounting to Php 4,650,000.
Private prosecutor Erwin Matib pointed out that the amount categorized as non-compensation income was higher than Duterte’s compensation as Davao City mayor.
Matib suggested that the larger amount represented earnings from the practice of her profession, prompting an objection from defense counsel Kristine Ferrer.
Ferrer argued that the term “practice of profession” did not appear in Duterte’s income tax return and maintained that the prosecution should adhere to the actual descriptions contained in the document.
Garcia-Marquez clarified that the Annual Income Tax Return identified the amount under the category “sales, revenues, receipts, fees,” without specifically describing it as income from professional practice.
Senator-judge Panfilo Lacson also intervened, pointing out that Duterte was not yet serving as vice president in 2021.
Matib responded that the prosecution was examining restrictions applicable to city mayors, explaining that the testimony was intended to establish what prosecutors alleged was a pattern or habit of violating laws prohibiting certain public officials from practicing their professions.
Ferrer reiterated that the prosecution should limit its characterization of the income to what was expressly stated in the tax documents.
The exchange highlighted a disagreement between the prosecution and defense over whether Duterte’s reported non-compensation income could be treated as evidence of professional practice while she held public office.
The BIR testimony established the amounts and classifications appearing in the tax return but did not, by itself, determine whether the income came from professional practice or whether any law had been violated.
The matter remains subject to examination by the Senate impeachment court as the prosecution continues presenting financial evidence in the trial.