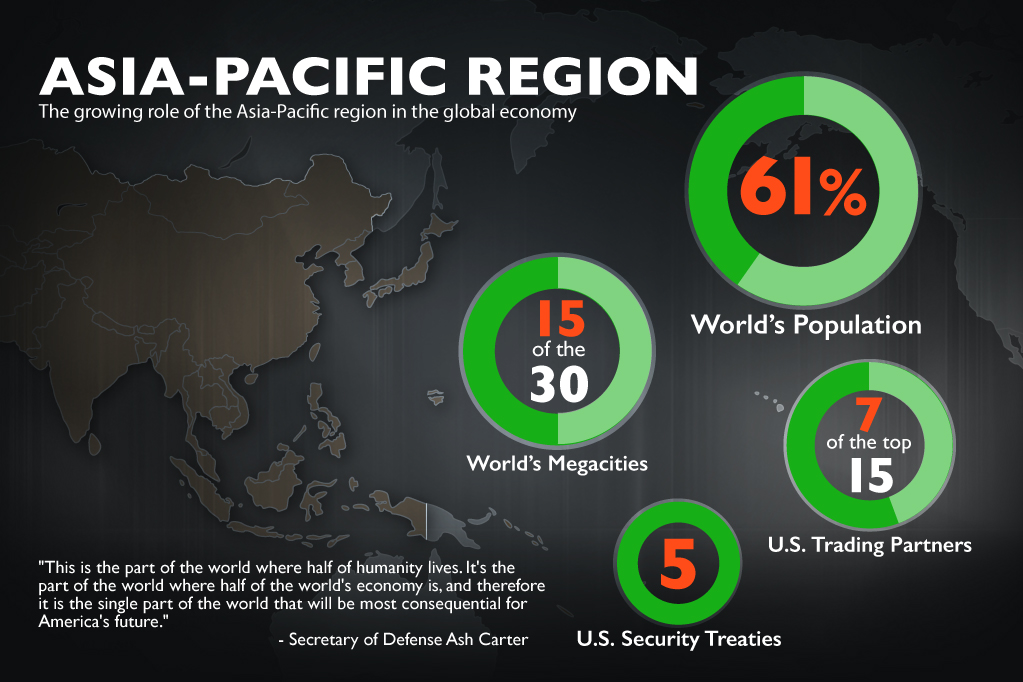

Asia-Pacific economies are navigating a turbulent economic landscape, as shifting U.S. trade policies, fluctuating domestic demand, and nuanced inflation dynamics shape the region’s outlook, according to Moody’s Analytics Weekly Asia-Pacific Economic Review.
Moody’s Analytics noted a brief moment of relief for Asia-Pacific exporters this week as a U.S. court ruled against the bulk of global tariffs imposed under former President Donald Trump. However, the celebration was short-lived.
An appeals court immediately issued a stay, leaving the contested tariffs in place pending a final ruling. The White House has signaled it is prepared to escalate the matter to the Supreme Court if necessary and will continue negotiations with trading partners in the meantime.
For South Korea, this uncertainty is especially costly. A 25% tariff on automobiles, steel, and aluminum remains, and although a harsher 25% duty on other goods was paused, it has only been replaced with a temporary 10% levy.
Seoul is pursuing exemptions by offering investment cooperation in sectors like shipbuilding and energy, but even favorable outcomes may not insulate it from broader U.S. tariff actions targeting global supply chains.
In brighter news, a meeting between ASEAN members and the Gulf Cooperation Council in Malaysia concluded with a mutual commitment to deepen trade and investment ties. Officials agreed to explore the feasibility of a free trade agreement, signaling growing inter-regional collaboration amid global economic fragmentation.
South Korea cuts rates amid political turmoil
The Bank of Korea (BoK) responded to deteriorating domestic conditions by cutting its policy rate by 25 basis points to 2.5%, marking the fourth cut since October. The decision came just ahead of a crucial presidential election on June 3, which may offer political stabilization following last year’s controversial martial law declaration and the impeachment of President Yoon Suk Yeol.
Despite a rebound in consumer sentiment—May’s index rose to 101.8, its highest since November 2024—the South Korean economy remains under strain. GDP shrank 0.2% in the March quarter, the first contraction since mid-2024, and both industrial production and retail sales fell 0.9% month-on-month in April. Forecasts for 2025 growth have been downgraded to just 0.6%.
Still, a combination of stable inflation—hovering near the BoK’s 2% target—and a strengthening won offers room for further easing, with another rate cut expected later this year.
Japan’s inflation ‘spike’ misleading, production slips
In Japan, alarm bells rang as core consumer inflation rose to 3.5% year-on-year in April, the highest since early 2023. But analysts caution that the increase is largely cosmetic. Japan’s core CPI strips out only fresh food—not all food and energy—making it less useful for gauging underlying price trends. The more telling “super-core” inflation rate held steady at a benign 1.6%.
Headline inflation remained at 3.6%, driven by reduced government energy subsidies, while food price contributions actually declined. Most categories were flat, and service inflation—a key concern for the Bank of Japan—edged down to 1.3%, reinforcing the view that domestic demand remains soft.
Meanwhile, Japanese industrial production dipped 0.9% in April, a sign that exporters are feeling the pressure from foreign competition, lackluster local demand, and ongoing trade friction.
Taiwan moderates growth expectations
Taiwan’s economy expanded 1.8% in the March quarter, slower than the previously estimated 2.3%. Nevertheless, officials are holding firm to a 2025 growth forecast of 3.1%.
Taiwan’s export-heavy economy is closely tied to global tech and semiconductor cycles, and further clarity on U.S. trade policy could heavily influence outcomes in the second half of the year.
Outlook: Cautious optimism with political and trade caveats
While some green shoots of recovery—like improving consumer confidence and regional trade diplomacy—are visible, Asia-Pacific’s economic health remains hostage to volatile geopolitical dynamics, including the uncertain fate of U.S. tariffs and domestic political stability in key markets.
Central banks may continue easing to support growth, but without resolution on trade tensions, headwinds will persist.